Business is busy. Customers are buying. Invoices are going out. Sales might even be better than they were last year.
So why does paying the bills still feel like a monthly emergency?
You check the business bank account, mentally subtract a few upcoming payments, and suddenly that healthy sales month doesn’t look so healthy anymore.
It’s frustrating, especially when you’re working harder than ever and can’t figure out where the money is going.
The problem may not be how much money your business makes. It may be when that money comes in, where it goes, and how much of it is actually available to spend.
And those are three very different things.
Making Sales Doesn't Mean You Have Money Available
One of the biggest financial misconceptions small-business owners run into is treating sales, profit, and available cash as though they’re interchangeable.
They’re not.
Revenue is the money your business earns from selling products or services.
Profit is what’s left after subtracting business expenses from revenue, based on the accounting method used.
Cash flow tracks money moving into and out of your business.
Here’s a hypothetical example.
Your business generates $30,000 in sales during the month. Your profit and loss report shows $8,000 in profit.
Not bad, right?
But there’s a catch.
Some customers haven’t paid their invoices yet. You made a loan payment, purchased inventory for next month, and paid an overdue supplier balance.
Suddenly, the amount sitting in your bank account looks nothing like that $8,000 profit.
That’s not necessarily a bookkeeping error. It’s often the result of transactions affecting your profit and cash at different times.
A business can be profitable on paper and still struggle to pay its bills.
Understanding why starts with looking beyond the sales numbers.
7 Reasons Your Business Makes Money but Still Feels Broke
1. Your Customers Aren’t Paying as Quickly as Your Bills Come Due
You finish a $5,000 project and send the customer an invoice with 30-day payment terms.
Meanwhile, you have payroll on Friday, rent due next week, and a supplier who expects payment immediately.
The revenue may already appear on your profit and loss report if you use accrual accounting, but that doesn’t put $5,000 in your checking account.
Until the customer pays, you’re financing the gap.
Now imagine several customers doing the same thing.
You could have $20,000 in outstanding invoices and still struggle to cover a $3,000 payment.
What to check: Review your accounts receivable aging report. It shows which customers owe you money and how long their invoices have been outstanding.
Look for overdue balances, customers who consistently pay late, and invoices that haven’t received follow-up.
If you regularly wait 30 to 60 days for payment while your own expenses are due sooner, your payment terms may need attention.
2. You’re Spending Money Before You’ve Accounted for Upcoming Bills
A large customer payment arrives. Your bank balance jumps to $15,000.
It looks like there’s plenty of money available.
But what if $4,000 is needed for payroll, $3,000 for supplier invoices, $2,000 for rent, and another $1,500 for upcoming expenses?
That leaves $4,500 before considering any additional obligations.
The problem is that your bank account doesn’t separate money you can safely spend from money you’ve already committed.
It simply shows what’s there.
This becomes particularly dangerous when business owners make purchasing decisions based on the current balance without considering what’s coming due.
What to check: Review unpaid bills, recurring expenses, upcoming payroll, and scheduled payments before deciding how much cash is available for new purchases.
3. Your Business Expenses Have Quietly Increased
Not every cash flow problem comes from a dramatic financial mistake.
Sometimes expenses simply creep upward.
Software subscriptions get added. Insurance premiums increase. Shipping costs rise. A supplier changes pricing. A few additional monthly services seem inexpensive individually.
And because the business is still making sales, nobody notices the cumulative effect.
A $75 subscription might not seem worth questioning. But ten recurring charges of $75 cost $750 every month, or $9,000 annually.
That’s real money leaving the business, whether anyone is using those services or not.
What to check: Compare your profit and loss reports over several months. Look at expenses as a percentage of revenue, not just their dollar amounts.
Pay particular attention to recurring charges, cost of goods sold, merchant processing fees, and expenses that have grown faster than sales.
4. You’re Making Sales, but Your Profit Margins Are Too Thin
More sales don’t automatically solve a money problem.
Imagine selling a product for $100.
After the product cost, shipping, processing fees, and other direct costs, you have $20 left to help cover overhead and generate profit.
If your operating expenses consume that remaining $20, increasing sales might create more work without producing meaningful profit.
It gets worse if your costs increase but your prices stay the same.
A business can have impressive revenue and still keep very little of it.
What to check: Review gross profit margins by product, service, or job when your records support that level of detail.
If you sell products, make sure you’re accounting for the costs required to get those products to customers. If you provide services, consider labor, subcontractors, and other direct service costs.
A busy business with weak margins can feel perpetually broke because very little money remains after the work is completed.
5. Loan Payments Are Taking More Cash Than Your Profit Report Shows
This one catches business owners by surprise.
You make a $1,200 monthly business loan payment. You expect your profit and loss report to show a $1,200 expense.
But it generally won’t.
The interest portion is typically recorded as an expense. The principal portion reduces the loan liability on your balance sheet.
Both portions reduce your available cash.
So your business might show a reasonable profit while a significant amount of money is going toward loan principal payments that don’t appear as expenses on the profit and loss report.
What to check: Review your loan balances and monthly payment schedules alongside your profit and loss report and cash flow information.
If you’re relying exclusively on your profit report to determine how much money is available, you’re missing an important part of the picture.
6. You’re Not Setting Aside Money for Taxes
Your business has a strong month, and you use the available cash to cover operating expenses, purchases, and other business needs.
Then a tax payment comes due.
The money that should have been reserved is already gone.
For many small-business owners, taxes don’t automatically come out of every customer payment the way withholding works for employees.
Depending on how your business is structured and taxed, you may need to make estimated tax payments during the year.
Sales tax collected from customers, where applicable, can create another problem if it’s treated as available business cash instead of an amount owed to the taxing authority.
What to check: Review your tax obligations with your tax professional and establish a process for reserving funds as money comes in.
Your bookkeeping should also distinguish between business income, tax liabilities, and payments made toward those liabilities.
7. You’re Taking Money Out of the Business Without Tracking Its Impact
Business owners need to get paid. That’s part of running a business.
But the way money moves from the business to the owner matters.
Depending on the business structure, payments to owners may be recorded as payroll, owner draws, distributions, or other transactions.
Some of these reduce business cash without appearing as expenses on the profit and loss report.
For example, an owner’s draw generally reduces cash and owner’s equity, not business profit.
If you’re looking at a profitable month without considering the money you’ve withdrawn, the remaining bank balance can be confusing.
What to check: Review owner withdrawals separately from ordinary operating expenses. Make sure they’re categorized correctly and included in your cash planning.
The goal isn’t to stop paying yourself. It’s to understand how those payments affect the cash your business needs to operate.
How to Find Out Where Your Money Is Going
If your business consistently makes sales but struggles to pay bills, start by examining a few specific reports.
You don’t need to become an accountant. You do need reliable numbers.
Start With Your Profit and Loss Report
Your profit and loss statement shows revenue and expenses for a selected period.
Look at the last three to six months.
Are sales increasing while profits remain flat? Are certain expenses growing faster than revenue? Are you earning enough to cover normal operating costs?
If the business is losing money, that’s a different problem from being profitable but temporarily short on cash.
You need to know which problem you’re dealing with before trying to fix it.
Review Your Balance Sheet
Your balance sheet helps explain what the business owns, what it owes, and the owner’s equity.
Pay attention to accounts receivable, inventory, credit card balances, loans, and other liabilities.
For example, increasing inventory might explain why cash is disappearing even though those purchases haven’t all become expenses on your profit and loss report.
Likewise, paying down loan principal reduces cash and debt without reducing profit.
Look at Your Cash Flow Statement
Your cash flow statement helps connect the dots.
It separates cash movements into operating, investing, and financing activities.
That distinction matters.
Cash spent on equipment, loan principal payments, and certain owner distributions can reduce your bank balance without showing up as ordinary operating expenses.
If you have reliable records, this report can help explain why your profit and available cash are telling different stories.
Check Your Accounts Receivable and Accounts Payable
Two additional reports deserve attention:
- Accounts receivable aging: Who owes your business money, how much, and how long they’ve owed it.
- Accounts payable aging: Which bills your business owes and when they need to be paid.
Together, these reports help you see whether incoming customer payments are likely to arrive before your own obligations come due.
A profitable business can run into trouble simply because those dates don’t line up.
What to Do When Your Business Is Profitable but Short on Cash
Once you understand the cause, you can start making changes.
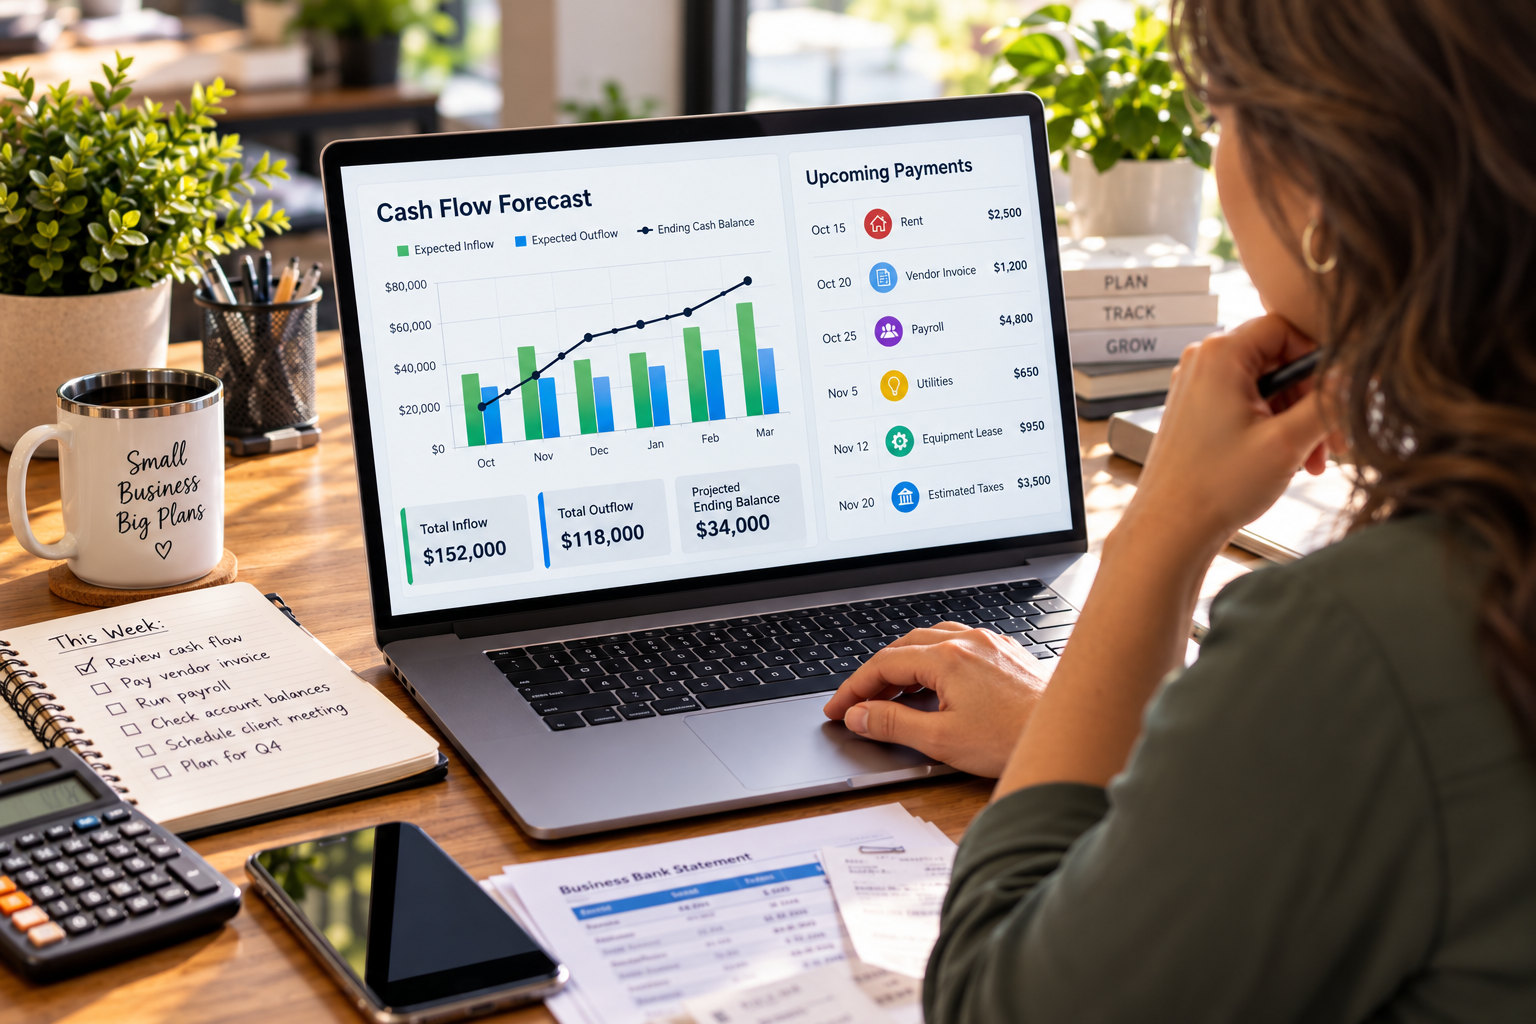
Build a Short-Term Cash Flow Forecast
Start with a simple 30-day forecast.
List the cash currently available, customer payments you realistically expect to receive, and bills that need to be paid.
Include payroll, rent, loan payments, taxes, supplier invoices, and recurring expenses.
Use expected payment dates rather than assuming every outstanding invoice will be collected immediately.
This helps you identify shortages before they happen.
If a large payment is due next Friday, it’s better to discover the potential problem today than Thursday afternoon.
Make Invoice Follow-Up Part of Your Routine
If slow customer payments are creating cash shortages, review your invoicing process.
Send invoices promptly. Make payment terms clear. Follow up on overdue balances consistently.
For some businesses, deposits, progress billing, or shorter payment terms may help reduce the gap between doing the work and receiving payment.
Review Pricing and Expenses Together
Cutting costs may help, but don’t assume expenses are the only issue.
If your prices don’t adequately cover the cost of providing your products or services, reducing a few subscriptions won’t fix the underlying problem.
Review both your costs and your pricing.
Look at which products, services, or jobs generate healthy margins and which ones consume resources without leaving enough profit.
Keep Your Bookkeeping Current
Trying to understand a cash shortage using financial records that haven’t been updated in three months is difficult.
Unrecorded transactions, unreconciled accounts, duplicate expenses, or incorrectly categorized payments can make your reports misleading.
A particularly common source of confusion is using accounting software primarily to create invoices while neglecting the bookkeeping behind those invoices.
Sending an invoice tells you what a customer owes. It doesn’t tell you whether your business can afford next week’s bills.
Regular bookkeeping helps keep the financial information current enough to make useful decisions.
And that’s the real benefit: fewer surprises.
Your Business Shouldn't Be a Financial Guessing Game
If your business is making sales but never seems to have enough money, don’t automatically assume you need more customers.
You might.
But you might also need to collect payments faster, adjust pricing, control expenses, plan for taxes, or better understand where your cash is going.
The first step is identifying the actual problem.
A bank balance can tell you how much money is there right now. It can’t tell you how much of that money is already committed, why your profit doesn’t match your cash, or whether you’ll have enough to cover next month’s obligations.
That’s what good financial records help you understand.
Need Help Making Sense of Your Business Finances?
At Zia Bookkeepers Group, we help small-business owners organize and maintain their financial records so they can better understand what’s happening in their businesses.
If your sales look healthy but your bank account tells a different story, we can help you take a closer look at your bookkeeping.
Schedule a free consultation to discuss your business’s bookkeeping needs and find out what your financial records may be telling you.